Key Points
- AUD pricing does not guarantee fee-free payments. An Australian bank can classify a payment as international because the merchant or processor is overseas—even when the transaction is charged in AUD.
- Some bank products apply a 3% international transaction fee, but rates and exemptions vary. Check the terms for your exact card or account.
- A casino’s “no deposit fees” claim may describe only its own charges. Your bank can still apply a separate fee.
- International transaction fees, exchange-rate margins, dynamic currency conversion and intermediary bank deductions are different costs.
- Choosing AUD through dynamic currency conversion can involve a marked-up exchange rate while still attracting an issuer’s international fee.
- Small percentage fees accumulate. At 3%, A$2,400 in qualifying transactions produces A$72 in additional charges.
- Withdrawals can also arrive short because of intermediary or recipient-bank deductions. A smaller payment does not automatically establish that the casino withheld the difference.
- Refunds do not necessarily reverse every cost. Reconcile the original debit, fees, refund and any later adjustments.
- If a charge is unexpected, save the payment records, check your product terms and ask the bank why it classified the transaction as international. A refund is not guaranteed.
- Lower payment costs do not make an offshore casino safe or authorised to serve Australians. Do not deposit again or gamble more to recover a fee.
Why AUD Casino Payments Can Still Trigger International Fees
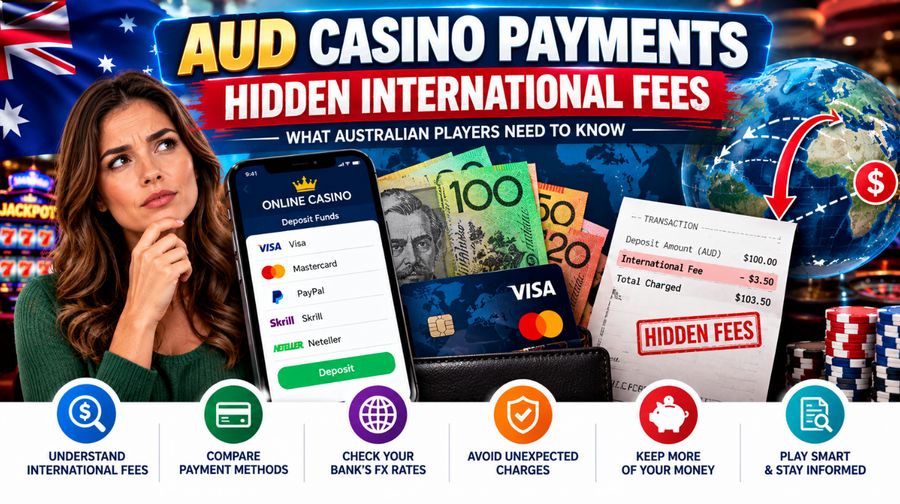
A casino displays your balance in AUD. You deposit A$200. Your bank account is debited A$206.
The extra A$6 is not a gambling loss. It is a payment cost—and the Australian-dollar display did not prevent it.
The explanation is often an international transaction fee. Some Australian banks apply these fees when a merchant or processing entity is overseas, even if the transaction is charged in Australian dollars.
That distinction matters. The payment does not necessarily need to be converted into euros, US dollars or another currency for the fee to apply.
An offshore casino’s payment arrangements can involve an overseas merchant, acquiring institution or processor. However, it would be misleading to claim that all AUD casino payments travel through European banks. The processing location needs to be established for the particular transaction.
It would also be inaccurate to call every extra charge a conversion fee. Bank international transaction fees, exchange-rate margins and intermediary bank deductions are different costs.
The real problem is the gap between what the cashier displays and what your account ultimately loses.
For Australian pokies consumers, “AUD accepted” answers a currency question. It does not answer where the payment is processed, which fees apply or whether the gambling service is authorised to serve Australians.
Why an AUD Payment Can Still Attract an Overseas Fee
A transaction has more than one relevant characteristic.
Its currency is one. The location of the merchant or processing entity is another.
An account can display A$200 and receive an A$200 transaction while the card issuer classifies the payment as international because of the overseas business or processing arrangement.
Westpac’s published credit-card fee information illustrates this distinction. Its 3% foreign transaction fee covers transactions in foreign currency, or in any currency with a merchant or processing entity outside Australia. The page also identifies product exceptions.
ANZ Plus publishes a 3% charge for relevant overseas or foreign-currency card transactions. It explicitly warns that overseas processing can attract the fee even when the customer is in Australia.
These are product-specific examples, not a universal Australian rate.
The ACCC likewise warns that an Australian-looking website or AUD prices do not establish that payment processing occurs domestically.
The lesson is simple: currency and processing location are separate facts.
The Four Costs People Commonly Confuse
“FX fee” is often used as a catch-all expression. That makes statements harder to interpret.
The person applying each charge can differ.
A casino might impose no deposit fee while your bank applies an international transaction fee. A transfer provider might advertise no fee while incorporating a margin into its exchange rate.
A withdrawal can also lose money through transfer deductions rather than card charges.
To understand the cost, identify the payment method, the transaction currency, the processing arrangement and the party applying the charge.
A single label cannot reliably explain the whole payment chain.
“No Deposit Fees” Does Not Mean No Banking Costs
A cashier can truthfully state that the operator does not charge a deposit fee while the transaction still costs more than the amount credited.
That wording describes the operator’s own charge. It does not necessarily describe your bank’s treatment.
Suppose the casino credits A$200 and adds no surcharge. Your issuer then applies a 3% international transaction fee.
The results are:
-
Casino credit: A$200.
-
Bank fee: A$6.
-
Total account debit: A$206.
The casino’s “no deposit fee” statement and the bank charge can coexist.
The concern is whether the payment information leaves a misleading overall impression, especially if the business appears Australian.
The ACCC advises businesses processing payments overseas to alert customers before payment where international transaction fees are likely.
An operator’s generic “third-party fees may apply” clause also deserves scrutiny. It may identify a possibility without explaining enough for a customer to predict the final debit.
The practical question is not “Does the casino charge a fee?” It is “What is the total cost to my account?”
What an Overseas Processor Actually Changes
An online card payment involves institutions beyond the merchant.
The acquiring side accepts or processes the payment for the business. Your issuing bank handles your card account. Payment networks connect the transaction.
An overseas participant can affect how your issuer classifies the transaction under its terms.
ANZ’s personal-account fee document specifically includes purchases processed by an overseas financial institution. It also describes circumstances involving an intermediary outside Australia.
This establishes why an AUD payment can attract an overseas charge. It does not establish the route used by a particular casino.
A statement descriptor alone may not identify every institution involved. The casino’s brand, the payment processor and the legal merchant can have different names.
If the route matters to a fee dispute, ask the bank which transaction attributes triggered the charge.
Do not assume a European location simply because an unfamiliar name appears. Equally, do not assume domestic processing because the casino uses Australian branding.
The Cost of a 3% Fee Over Time
An isolated A$3 charge looks small. Repetition changes the picture.
At a hypothetical 3% rate:
These figures describe a fee applied to the transaction amount. They do not include conversion margins, provider charges or gambling losses.
Consider someone making twelve A$200 deposits during a month.
The deposits total A$2,400. A 3% fee on each produces A$72 in banking charges. If that pattern continued for twelve months, the charges would total A$864.
This is an illustration, not a recommended spending pattern.
The important point is that percentage fees scale with activity. Breaking the same total into smaller transactions does not reduce a purely percentage-based charge.
If minimum or fixed fees also apply, splitting payments can make costs worse.
A “Break-Even” Casino Session Can Still Lose Money
Payment costs sit outside the game outcome.
Suppose a fictional player deposits A$500, incurs a A$15 international transaction fee and later receives A$500 back without further deductions.
The game balance has broken even. The bank balance has not.
The account is A$15 lower.
If the withdrawal also incurs a fee, the difference becomes larger.
This is why game results and payment results should be tracked separately:
-
Total deposits credited.
-
Total amounts debited by the bank.
-
Withdrawals requested.
-
Withdrawals actually received.
-
Separate banking or provider charges.
The cashier balance cannot represent your complete financial result.
The same distinction applies to a winning session. A displayed profit may be reduced by payment costs before it reaches an Australian account.
Understanding this should discourage chasing—not encourage further wagering to recover the fee.
Dynamic Currency Conversion: The AUD Option Is Not Always Cheaper
Dynamic currency conversion, commonly called DCC, occurs when a merchant or its provider offers to convert a foreign-currency transaction into your home currency.
It can make the price easier to understand because the amount is presented in AUD.
That convenience does not establish good value.
The ACCC warns that choosing AUD can be more expensive because the overseas provider may add a margin to the conversion rate. The card issuer may still apply an international transaction fee.
Two costs can therefore coexist:
-
A less favourable conversion rate.
-
An issuer’s overseas transaction fee.
However, not every AUD payment is DCC.
A merchant can genuinely price its service in AUD without first presenting another currency for conversion. That transaction may still attract an international fee because of overseas processing.
Before identifying a charge as DCC, establish whether a conversion occurred and who performed it.
For this article, the aim is explaining the distinction—not recommending payment methods for accessing prohibited offshore gambling services.
Exchange-Rate Margins Are Less Visible Than Separate Fees
A bank fee often appears as an identifiable statement entry. An exchange-rate margin may be embedded in the converted amount.
Consider a fictional transaction worth A$200 at a benchmark rate.
If the provider’s rate produces an A$208 charge, the A$8 difference is a conversion cost in this simplified example. There may be no separate entry labelled “conversion fee”.
A further 3% charge on A$208 would add A$6.24, producing an A$214.24 total.
Real comparisons require care. Currency prices move, and the relevant transaction and settlement times may differ. A rate seen later is not necessarily the rate available when the payment was processed.
The ACCC recommends comparing total prices, including exchange-rate margins and fees. It also recommends comparing rates at the same time.
“Fee-free” is therefore not a complete price description. A poor exchange rate can cost more than an explicit fee.
Withdrawal Transfers Can Lose Money Through Another Route
Card deposit fees and bank-transfer deductions are not the same mechanism.
An international withdrawal may involve intermediary or correspondent banks before reaching the recipient.
Westpac’s international payment information warns that overseas institutions may impose charges or convert a payment’s currency. It also notes that some costs can be deducted from the amount transferred.
In a fictional example:
-
Withdrawal sent: A$1,000.
-
Intermediary deduction: A$15.
-
Recipient-bank deduction: A$10.
-
Amount received: A$975.
Those figures illustrate the mechanism. They are not standard casino charges.
The relevant evidence includes the sender’s payment confirmation, transfer currency, route and any trace information the institutions can provide.
A casino saying it sent the full amount does not establish that the recipient receives the full amount.
Likewise, a smaller credit does not automatically prove that the casino withheld the difference.
Identify where the deduction occurred before assigning responsibility.
Do Refunds Automatically Reverse the Fee?
Do not assume that a refunded payment leaves no cost.
Refund treatment depends on the bank product and transaction circumstances.
ANZ’s personal-account fee terms define relevant international transactions to include certain credits, refunds and reversals. ANZ Plus also identifies reversals among possible overseas transactions.
That does not mean every refund necessarily attracts a new fee. It means the outcome cannot be inferred from the original purchase alone.
Currency movement can also affect foreign-currency refunds. The AUD value returned may differ from the amount originally debited.
When checking a refund, reconcile:
-
The original debit.
-
Any original fee.
-
The refund credit.
-
Any later charge or fee reversal.
A pending entry is not always the final posted result.
Ask the issuer to explain the complete sequence rather than treating the visible refund amount as the end of the matter.
Why the Charge Can Feel Hidden Without Being Undisclosed
“Hidden” can describe the customer’s experience without establishing that the bank breached its disclosure obligations.
The fee may appear in product terms while the merchant’s checkout provides no obvious indication that the transaction is international.
That mismatch has drawn regulatory attention.
In 2016, ASIC announced that Westpac would refund A$20 million in foreign transaction fees after disclosure issues concerning certain AUD overseas transactions.
The case is historical. It does not establish that today’s Westpac fees are invalid or that every customer deserves a refund.
It does demonstrate that AUD transaction disclosure is a real consumer issue—not merely confusion about foreign exchange.
ASIC explained that international fees can apply to AUD transactions involving overseas merchants, institutions or processing.
The correct question is whether the particular fee was disclosed and correctly applied—not whether the amount happened to display an Australian dollar symbol.
How to Investigate an Unexpected Charge
Reconcile the Amounts
Compare the cashier receipt with the final posted debit.
Separate the principal payment, issuer fee and any other entry. Avoid relying exclusively on pending transactions.
Check the Product Terms
Use the terms for your exact card or account.
A bank’s headline rate may not apply to every product. Westpac’s published page, for example, identifies exceptions to its standard foreign transaction charge.
Rates also differ between product categories.
Ask the Bank a Specific Question
Request the reason the payment was classified as international.
Ask whether the trigger was foreign currency, merchant location or processing location.
Also ask which amount formed the fee calculation.
Preserve the Checkout Information
Save any statement about AUD charging, local processing or deposit fees.
Those claims can matter when explaining why the charge was unexpected.
Avoid Further Test Payments
Another deposit is not necessary to demonstrate the first fee.
If the transaction concerns an illegal offshore casino, reducing further exposure is more important than experimenting with its payment routes.
Can You Challenge the Fee?
A correctly applied, adequately disclosed charge is not automatically refundable.
However, you can ask the bank to investigate if the fee appears incorrectly calculated, inconsistently applied or connected to misleading payment information.
The ACCC says consumers can request a fee refund from their issuer where an unexpected international transaction fee accompanies an AUD purchase from a business that appeared Australian.
That is guidance about seeking a remedy, not a guaranteed outcome.
Raise the matter with the bank’s internal complaint process and retain the response.
AFCA provides a free, independent complaint service for relevant financial firms. Its published information says it can consider certain fees that were incorrectly applied or calculated.
AFCA should not be presented as a way to recover gambling losses simply because the activity involved a card.
A fee dispute, an unauthorised-payment claim and a complaint about unpaid casino winnings are different matters.
Describe the facts accurately.
Lower Payment Costs Do Not Make Offshore Casinos Safe
The Australian legal position remains separate from the fee question.
Offshore operators cannot lawfully provide online casino-style services to people located in Australia. Displaying AUD or using a particular processor does not change that.
ACMA warns that illegal operators can expose customers to withheld winnings, disappearing balances and unauthorised withdrawals.
A payment product with fewer international fees would not remove those risks. Nor should another payment method be treated as a workaround for restrictions.
This article is about identifying charges and protecting an Australian bank account—not optimising access to illegal casinos.
For ordinary lawful overseas purchases, understanding total cost can help consumers compare options. For offshore gambling, the more important decision is avoiding additional exposure.
Do not gamble again to recover a banking charge. A small fee can become the starting point for a much larger loss.
Final Verdict
An AUD display does not guarantee domestic processing or a fee-free transaction.
The key is classification: your issuer may treat the payment as international because of an overseas merchant or processor, even when no currency conversion occurs.
Exchange margins, DCC and intermediary transfer deductions are separate mechanisms. Identifying them accurately is the first step towards understanding or disputing a charge.
Check the final debit, exact product terms and processing explanation. Avoid unsupported claims about European routes, universal 3% rates or guaranteed refunds.
For gambling support in Australia, call the National Gambling Helpline on 1800 858 858, available free and confidentially, 24/7.
Frequently Asked Questions
Why did my bank charge an international fee on an AUD casino deposit?
An AUD transaction can still be classified as international if the merchant or processing entity is overseas. The currency displayed in the casino cashier does not establish where the payment is processed. Ask your bank which transaction attributes triggered the fee.
Do all Australian banks charge a 3% overseas transaction fee?
No. Rates, definitions and exemptions vary between banks and individual products. Some products discussed in the article charge 3%, but that is not a universal rate. Check the current terms for your exact card or account rather than relying on a bank’s general fee page.
Does “no deposit fees” mean the payment will cost nothing extra?
Not necessarily. A casino may charge no deposit fee while your bank applies a separate international transaction fee. For example, a A$200 deposit with a 3% issuer fee costs A$206, even if the casino credits the full A$200.
Are international transaction fees the same as currency conversion fees?
No. An international transaction fee can apply without any currency conversion. An exchange-rate margin is a cost embedded in the conversion rate, while an intermediary deduction is a charge associated with a transfer route. These costs can occur separately or together.
Does choosing AUD at checkout avoid foreign transaction fees?
Not automatically. AUD pricing does not prevent an issuer from applying a fee because of overseas processing. If the AUD option involves dynamic currency conversion, it can also include a marked-up exchange rate. Identify how the AUD amount was calculated before assuming it is cheaper.
Do offshore casinos always route Australian payments through European banks?
The article does not establish that. An offshore payment can involve an overseas merchant, processor or financial institution, but its location must be verified for the particular transaction. An unfamiliar statement description alone is not enough to identify the complete payment route.
Why did my casino withdrawal arrive with money missing?
An international transfer can incur intermediary or recipient-bank deductions. Currency conversion can also affect the final amount. Compare the withdrawal confirmation with the amount received and request the relevant payment details before assuming that the casino withheld the difference.
Will a refund automatically reverse the international transaction fee?
Do not assume it will. Treatment depends on the product terms and transaction circumstances. Reconcile the original debit, fee, refund credit and any later adjustments. Where foreign currency is involved, exchange-rate movement can also change the AUD amount returned.
Can I dispute an unexpected international transaction fee?
You can ask your bank to investigate whether the fee was correctly calculated, applied and disclosed. Keep the receipt, final statement entries and any checkout claims about AUD charging or processing. If the matter remains unresolved, an eligible complaint may be taken to AFCA. A refund is not guaranteed.
Does avoiding international fees make an offshore casino safe?
No. Lower banking costs do not establish operator reliability, protect your balance or authorise prohibited online casino services in Australia. The priority is consumer protection, not finding a cheaper route to deposit. Do not send more money or gamble again to recover a fee.
Sources
- ACCC: AUD overseas processing, dynamic currency conversion, exchange margins and unexpected-fee guidance
- Westpac: Published foreign transaction fee, overseas-processing definition and product exceptions
- ANZ Plus: International card fees and overseas processing while the customer is in Australia
- ANZ: Personal-account fee definitions covering overseas institutions, intermediaries and relevant credits
- Westpac: International payment margins and possible overseas bank deductions
- ASIC: Historical disclosure case and explanation of foreign transaction fees on AUD payments
- AFCA: Free financial complaint service and initial complaint steps
- AFCA: Complaints involving incorrectly calculated or applied fees
- ACMA: Australian restrictions on online casino services
- ACMA: Consumer risks from illegal gambling operators
- Department of Social Services: National Gambling Helpline and Australian support
Last Updated on October 14, 2026 by Pokie-Player